NFA Annual Questionnaire

Reminder to NFA Member Firms

As part of the annual processes and procedures NFA Members will need to make sure that they complete the NFA Annual Questionnaire.  As discussed below in the NFA’s most recent notice to members, it is important that NFA Members complete the questionnaire because some of the answers will appear as BASIC entries sometime within the first half of 2010 (for an image of this, please see Notice to Members I-10-02, reprinted in full below).  Below we have provided an overview of the major items which are addressed on the questionnaire.  NFA Members are urged to complete the NFA’s Self Exam Checklist prior to logging in to complete the questionnaire.

Questionnaire Items

The annual questionnaire actually requires the NFA Member to provide fairly detailed information on the nature of the Member’s business and the extent in which the Member participates in certain aspects of the industry such as trading in the forex markets.  Each firm will need to complete a section called “Firm & DR Information” as well as one section (or multiple sections if applicable) devoted to CTA, CPO, IB, or FCM specific questions.  Below we’ve outlined the major categories.

CTA Questionnaire

The central part of the CTA questionnaire focuses on information related to the trading program.  Such information requested includes: nominal AUM, forex account information, number of accounts trading Securities Futures Products (SFPs)*, most recent disclosure document date, whether any exemptions exist, types of investors, etc.

* A securities futures contract is a legally binding agreement between two parties to purchase or sell in the future a specific quantity of shares of a single equity security or narrow-based securities Index (e.g. products traded on One Chicago or NQLX). It does not include broad-based indices such as the S&P 500 or Dow.

CPO Questionnaire

The central part of the CPO questionnaire focuses on information related to the commodity pool.  Such information requested includes: pool trading information, question on restrictions (if any), forex trading information (if applicable), SFP trading (if applicable), most recent disclosure document date, whether any exemptions exist, etc.

Firm & DR Information

In the Firm & DR Information section you will need to include certain information on the preparer (name, title, phone, email) and you will need to complete firm information and disaster recovery information.

Firm Information

For the firm information there are a number of questions regarding the number of accounts to which the firm is currently providing advice, whether the firm is engaged in forex activities, the extent to which the firm utilizes advertising (tv/radio, print, internet), and/or whether the firm is registered in other capacity.  Importantly, there is a question regarding whether the firm has completed the self-exam checklist within the last 12 months.

Disaster Recovery Information

All NFA Member firms are required to have addressed disaster recovery.  For the purposes of the questionnaire, Members are required to provide primary and secondary contact information.  Specifically, the instructions are as follows:

For purposes of business continuity and disaster recovery, members are required to provide NFA with the name and contact information for one or two persons who NFA can contact during an emergency. Since this information will serve as an alternative contact in the event you are unable to continue doing business at your main location, the contact information that you provide should be different from that of your main location.

****

Notice to Members I-10-02

January 6, 2010

Reminder to all Members to complete new questions in Annual Questionnaire assessing Member’s futures-related and off-exchange forex business

On November 30, 2009, NFA issued Notice to Members I-09-21 [HFLB Note: reprinted directly below] requesting all Members to complete a series of new questions located in the Annual Questionnaire assessing their futures-related business. Although some NFA Members have complied with this request, many have not. It is critical that Members access and complete questions in the Firm and DR Information section of the Annual Questionnaire as soon as possible. This applies not only to Members trading on-exchange futures products but also Members trading in the off-exchange foreign currency (forex) market.

Beginning in early 2010 NFA’s BASIC system will display information reflecting whether firms are actively engaged in futures-related business activity or not. If the questions are not answered, the answers will default to no activity, which is what will be displayed in BASIC, as illustrated below.

For additional information and instructions on accessing the Annual Questionnaire, click here.

If you have any questions, please contact NFA’s Information Center at 800-621-3570 or 312-781-1410.

****

Notice I-09-21

November 30, 2009

NFA adds new questions to Annual Questionnaire to assess Member’s futures-related business

NFA has approximately 500 firms that are NFA Members but have represented to NFA via their Annual Questionnaire that they are not doing any business that requires membership (“Inactive firms”). Almost universally, these Members indicate that they maintain their membership because they may do business in the future.

Since 2006, NFA has taken several Member Responsibility Actions against Member firms that had told NFA they were inactive. These actions were taken after NFA obtained information from reviewing the internet, through contacts with other NFA Members, and by receiving customer complaints suggesting that these firms were in fact active.

Due to these disciplinary actions, NFA’s Board of Directors requested that beginning in early 2010 NFA’s BASIC system display information reflecting whether firms are actively engaged in futures-related business activity or not. Presumably, if a Member is identified in BASIC as not conducting futures-related business, this will raise a “red flag” to potential customers who are being solicited by an Inactive Firm.

Specifically, BASIC will contain information regarding whether or not the Member has on-exchange customer accounts, manages customer accounts, operates pools, is engaged in retail off-exchange foreign currency activities and/or is soliciting customer business. This information will be based solely on information that Member firms provide in their responses to the questions in the Firm and DR Information section of the Annual Questionnaire.

NFA has re-designed this portion of the Annual Questionnaire by adding new questions and moving certain questions from other sections. Firms may update the answers in the Firm and DR Information section of the Annual Questionnaire at any time.

It is critical that Members access and complete questions in the Firm and DR Information section of the Annual Questionnaire as soon as possible. If the questions are not answered, the answers will default to no activity, which is what will be displayed in BASIC.

Please follow these instructions to access the Annual Questionnaire and provide the required information.

1. Open the Questionnaire system using this link: https://www.nfa.futures.org/AppEntry/Redirect.aspx?app=SPECIAL_QUESTION

2. Enter your ORS ID and password to logon.

3. From the “Online Questionnaire Index” screen, select “Firm and DR Information” under “Questionnaire Type.” (In addition, if you have not completed your most recent Questionnaire, you should update the previous version at this time.)

4. Update the Preparer Information on the next screen, if necessary, and then click “Next.”

5. To respond to this special request,

a. Answer the questions listed at the top of the screen under the heading “Please address the following questions regarding you firm’s business operations”.

b. After answering the applicable question(s), scroll to the bottom of the screen and click the “Submit Filing” button.

c. The system will then confirm that you submitted the updated Questionnaire to NFA.

If you have any questions about this Notice, please contact NFA’s Information Center at 800.621.3570 or 312.781.1410.

****

Other articles related to CTAs and CPOs include:

If you are a manager or firm that needs to register as a CTA or CPO, or if you are contemplating registration, please contact Bart Mallon, Esq. of Cole-Frieman &  Mallon LLP at 415-868-5345.
FLOORED Screening in San Francisco | 100 Women in Hedge Funds

Movie on Traders to be Screened in San Francisco

On January 28 the San Francisco investment management community will come together to watch the movie “FLOORED” which documents the issues facing floor traders as the industry continues its march away from traditional floor trading.  Please see the release below for more information.

Additionally, on an unrelated note, I would like to invite all futures/commodities professionals in the Bay Area to join the San Francisco Futures Professionals LinkIn Group.  The first meeting of this group will be sometime in February and will include traders/managers, service providers and (potentially) investors.

****

100whflogo

San Francisco Special Screenings of “FLOORED”
Followed by Director Q&A

January 28, 2010 at 5:00 and 7:30 PM
San Francisco, CA

Join us for sneak peek screenings of “Floored,” a feature-length documentary about the up and down lives of floor traders. Screenings will be followed by Q&A with Director James Allen Smith. (Run time: 80 minutes)

About the film: FLOORED is a gripping, honest look behind the curtain of the trading floor that few have ever seen. Like many aspects of our economy, computerized trading is changing the dynamics on the actual trading floors. FLOORED offers a unique window to this lesser-known world of finance.

To view the trailer and get more information on the film, please go to: www.FLOOREDmovie.com

Screening 1:
Time: 5:00pm wine reception/registration
Screening: 5:30- 6:45pm
Discussion: 6:45 – 7:15pm
Tickets cost $16 per person. Tickets can be purchased online at:
http://www.acteva.com/booking.cfm?bevaid=196294

Screening 2:
Time: 7:30 – 8:00pm registration
Screening: 8:00 – 9:15pm
Discussion: 9:15 – 9:45pm
Tickets cost $12 per person. Tickets can be purchased online at:
http://www.acteva.com/booking.cfm?bevaid=196297

We will begin promptly at screen times; please arrive early.

Location: The Roxie Theater
3117 16th Street, San Francisco, CA 94103

Directions
The Roxie Theater is located in the heart of San Francisco’s Mission District, at 3117 16th Street between Valencia and Guerrero. Local Muni are the 22 and 53 (both at 16th & Valencia), 33 (18th & Valencia), 14 (16th & Mission), 49 (16th & Mission). Bart stops one block east at 16th & Mission.

Public Parking is available on Hoff Street, off of 16th between Valencia and Mission. Very reasonable rates.
Click here for more directions

About 100 Women in Hedge Funds (www.100womeninhedgefunds.org)
100 Women in Hedge Funds is a global, practitioner-driven non-profit organization serving over 10,000 alternative investment management investors and professionals through educational, professional leverage and philanthropic initiatives. Formed in 2001, 100 Women in Hedge Funds has hosted more than 160 events globally, connected more than 150 senior women through Peer Advisory Groups and raised in excess of $17 million for philanthropic causes in the areas of women’s health, education and mentoring. For more information about 100 Women in Hedge Funds, please visit www.100womeninhedgefunds.org.

For questions, please email
Diane Schrader
Northern CA Chair, 100WHF
[email protected]

****

Bart Mallon, Esq. of runs the Hedge Fund Law Blog and provides hedge fund manager registration service through Cole-Frieman & Mallon LLP. He can be reached directly at 415-868-5345.

Hedge Fund Events January 2010

The following are various hedge fund events happening this month, including a networking event co-sponsored by Cole-Frieman & Mallon LLP in San Francisco on January 13.  Please email us if you would like us to add your event to this list.

****

January 6-8

January 11-13

January 12- 13

  • Sponsor: iGlobal
  • Event: 2nd Annual Carbon Trading Summit
  • Location: New York, NY
  • HFLB Note: we are very interested in this conference and about the carbon markets in general.  If any attendees of this conference want to [_____]

January 13

January 13-15

January 19

January 20

January 21

January 21-22

January 21-22

January 24-26

January 25 – 26

January 25-27

January 25-27

January 26-27

January 27

January 28

January 28-29

January 29

****

Bart Mallon, Esq. runs the Hedge Fund Law Blog and provides hedge fund formation and manager registration services through Cole-Frieman & Mallon LLP. He can be reached directly at 415-868-5345.

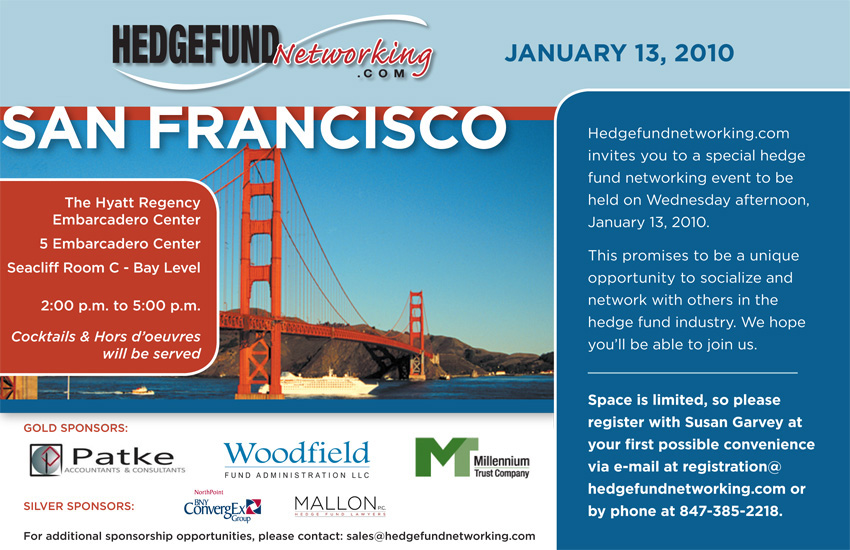
San Francisco Hedge Fund Networking Event

Cole-Frieman & Mallon LLP co-sponsors event at Hyatt Regency on January 13, 2010

On January 13 the San Francisco hedge fund community will be gathering at the Hyatt Regency in 5 Embarcadero Center for a networking event that will last from 2pm to 5pm.  Cocktails and hors d’oeuvres will be served and I look forward to having the opportunity to connect with clients, potential future clients, other service providers and colleagues.

Gold Sponsors
Patke & Associates
Woodfield Fund Administration, LLC
Millennium Trust Company

Silver Sponsors
NorthPoint BNY ConvergEx Group
Mallon P.C.

Space is limited, so please register with Susan Garvey at your first possible convenience via e-mail at [email protected] or by phone at 847-385-2218.

event invitation

event invitation

****

Bart Mallon, Esq. of runs the Hedge Fund Law Blog and provides hedge fund manager registration service through Cole-Frieman & Mallon LLP He can be reached directly at 415-868-5345.

Proposed Investment Adviser Regulations Overview

As we discussed in an earlier post, the SEC proposed new rules and amendments to existing rules under the Investment Advisers Act (the “Act”) to implement certain provisions of the Dodd-Frank Act related to hedge fund registration.

In summary, the new rules:

  • clarify eligibility for SEC registration for hedge fund and other asset managers
  • establish reporting requirements for certain “exempt reporting advisers”
  • require greater disclosure by registered IAs and each managed private fund in Form ADV
  • clarify the scope of new exemptions from SEC registration
  • propose amendments to the “pay to play” rules of the Act

This post will provide an overview of these proposals in greater depth.  Please feel free to comment below or contact us with your thoughts on the new rules as we are currently in the process of drafting a comment letter to the SEC about the proposed rules.

****

Rule 203A-1 Switching to or from SEC Registration

The new Rule 203A-1 provides state and SEC registered IAs with information on the time requirements for switching registration status.

State-registered switching to SEC-registered: After filing an annual amendment indicating eligibility for SEC registration (and not relying on an exemption from registration under sections 203(l) or 203(m) of the Act discussed below), apply for registration with the SEC within 90 days.

SEC-registered switching to State-registered: After filing an annual amendment indicating you are no longer eligible for SEC registration (and not relying on an exemption from registration under sections 203(l) or 203(m) of the Act discussed below), you must file Form ADV-W to withdraw SEC registration within 180 days of your fiscal year end (unless you are then eligible for SEC registration).  Note: during dual registration, the Act and applicable state laws apply.

For full text and overview please see our post on Rule 203A-1.

Rule 203A-5 IA Registration Transition Rules

IAs registered with the SEC on July 21, 2011 must report their AUM (via amendment to Form ADV) to the SEC by August 20, 2011, or 30 days after the effective date of the amendments, and to report the market value of its AUM determined within 30 days of the filing.  If such IAs are at that time below the threshold for SEC registration, the IA must withdraw from SEC registration by October 19, 2011 (and generally be registered with the state in which the adviser’s maintains its principle office and place of business).

In addition, the SEC is also proposing amendments to Form ADV which will require registered IAs to provide additional information regarding: (i) the private funds they advise, including AUM, the nature of the investors in the fund and the fund’s service providers; (ii) their advisory business, including information about the types of clients they have and potentially significant conflicts of interest; and (iii) additional information about non-advisory activities and financial industry affiliations.

For full text and overview please see our post on Rule 203A-5.

Rule 204-4 Reporting by Exempt Reporting Advisers:

Certain “exempt reporting advisers” exempt from SEC registration pursuant to Sections 203(l) and 203(m) of the Act (discussed below) must file Form ADV (but not Form ADV Part 2) with the SEC, following instructions specifically pertaining to such advisers.  Such advisers must file their initial Form ADV no later than August 20, 2011.

For full text and overview please see our post on Rule 204-4.

Rule 202(a)(30)-1 Foreign Private Adviser Exemption

This new exemption from SEC registration applies to “foreign private advisers.”

A “foreign private adviser” is an investment adviser that:

  • has no place of business in the U.S;
  • has less than $25 million in aggregate assets under management from U.S. clients and private fund investors;
  • has fewer than 15 U.S. clients and private fund investors; and
  • neither holds itself out to U.S. investors as an investment adviser nor acts as an investment adviser to any investment company registered under the Investment Company Act or any company that has elected to be a business development company.

“Foreign private advisers” do not need to comply with the reporting requirements under the new Section 204-4.

For full text and overview please see our post on Rule 202(a)(30)-1.

Rule 203(l)-1 Venture Capital Fund Exemption

This new exemption from SEC registration applies to advisers that solely advise “venture capital funds.”

A “venture capital fund” is a private fund that:

  • represents it is a venture capital fund;
  • invests in only equity securities of a portfolio company and 80% of such securities must have been acquired directly from the portfolio company;
  • has a management company which provides guidance to the portfolio company regarding management and operations of the portfolio company or the fund must control the portfolio company;
  • uses less than 15% leverage which may only be short term; and
  • provides fund investors with no withdrawal rights except in extraordinary circumstances.

The proposed rule also provides a grandfathering provision for certain presently existing venture capital funds.

For full text and overview please see our post on Rule 203(l)-1.

Rule 203(m)-1 Private Fund Adviser Exemption

This new exemption from SEC registration applies to advisers that solely advise private funds and have AUM in the U.S. of less than $150MM.  [HFLB note: the adviser may still be required to register pursuant to state law.]  The adviser must aggregate the value of all assets of the private funds it manages to determine whether it falls below the $150MM threshold.  AUM must be determined quarterly, with valuation based on the fair value of assets at the end of the quarter.  If an adviser’s AUM exceeds $150MM in private fund assets, the adviser must register as an investment adviser with the SEC within one calendar quarter.

For full text and overview please see our post on Rule 203(m)-1.

Rule 206(4)-5 Pay to Play Rules

Under the proposed amendment, an adviser would be permitted to pay a registered municipal advisor, instead of a “regulated person,” to solicit government entities on its behalf if the municipal advisor is subject to the Municipal Securities Rulemaking Board’s (the “MSRB”) pay-to-play rules.

****

As with any proposed rulemaking process, there are a number of ambiguities with respect to the proposals and a number of questions regarding the application of certain rules to the certain situations.  These issues are expected to be identified during the comment process and hopefully the SEC will be able to modify the proposed rules as appropriate when the final rules are promulgated.  One central open issue is the change from SEC to state registration for managers with less than $100MM AUM – it seems pretty clear that most states will not be able to handle an increase in the amount of managers that will be subject to state regulation.

As discussed in the proposals, public comments are due on January 24, 2011.

A full copy of the proposed rules are available here.

Comments received by the SEC on the proposed rules are available for review here.

****

Other related hedge fund articles:

Bart Mallon, Esq. runs the hedge fund law blog and provides registration and hedge fund compliance services to managers through Cole-Frieman & Mallon LLP.  He can be reached directly at 415-868-5345.

Qualified Eligible Person (QEP) Definition

The securities laws can be written obtusely and the definition of a qualified eligible person (QEP) may be one of the best examples of this.  There is no quick and easy definition of a what a QEP is so we are trying to make it as easy as possible to understand.  This post discusses the importance of the classification, provides the overview of the definition and then provides a link to the actual statutory language.

Why QEP Definition is Important for CPOs

The definition of QEP is important for commodity pool operators (CPOs) in a couple of situations.  The first is the 4.13(a)(4) exemption from the registration provisions for a CPO that provides advice to a commodity pool with only QEPs.  The second situation where a CPO will need to make sure the investors are QEPs is if they want to take advantage of the Rule 4.7 exemption.  The Rule 4.7 exemption allows CPOs to follow less-strict reporting requirements with regard to the commodity pool they manage.  These two exemptions essentially provide for reduced regulatory oversight of a CPO who provides advisory services to these class of investors.

Definition of QEP

A qualified eligible person is an investor who fits into one of two distinct groups: (1) investors who do not need to meet the portfolio requirement and (2) investors who need to meet the portfolio requirement.

1.  Investors who do not need to meet the portfolio requirement:

The following are considered to be QEPs regardless of whether or not they meet the portfolio requirement:

  • registered futures commission merchants
  • registered broker or dealers
  • registered commodity pool operators (under certain conditions, see rule for more details)
  • registered commodity trading advisors (under certain conditions, see rule for more details)
  • state or SEC registered investment advisers (under certain conditions, see rule for more details)
  • qualified purchasers
  • knowledgeable employee of the CPOs
  • certain persons related to advisers to exempt from registration as a CPO or CTA
  • trusts (under certain conditions, see rule for more details)
  • 501(c)(3) organizations (under certain conditions, see rule for more details)
  • non-United States persons
  • certain entities in which all of the owners/participants are QEPs

2.  Investors who need to meet the portfolio requirement:

The following will be considered to be QEPs only if they meet the portfolio requirement described below:

  • investment companies registered under the Investment Company Act (i.e. mutual funds)
  • certain business development companies (defined under both the Investment Company Act and Investment Advisers Act)
  • banks, savings and loan associations, and other like institutions acting for their own accounts or for the account of a QEP
  • insurance companies acting for their own account or for the account of a qualified eligible person
  • plans established and maintained by various governments and related bodies for the benefit of their employees, if such plan has total assets in excess of $5,000,000
  • employee benefit plans within the meaning of the ERISA (under certain conditions, see rule for more details)
  • 501(c)(3) organizations with total assets in excess of $5,000,000
  • corporations, business trusts, partnerships, LLCs or similar business ventures with total assets in excess of $5,000,000 and not formed for the specific purpose of participating in the exempt investment program
  • a natural person whose individual net worth, or joint net worth with that person’s spouse, at the time of either his purchase in the exempt pool or his opening of an exempt account exceeds $1,000,000 [HFLB note: this is one part of the accredited investor definition]
  • a natural person who had an individual income in excess of $200,000 in each of the two most recent years or joint income with that person’s spouse in excess of $300,000 in each of those years and has a reasonable expectation of reaching the same income level in the current year [HFLB note: this is one part of the accredited investor definition]
  • pools, trusts, insurance company separate accounts or bank collective trusts, with total assets in excess of $5,000,000 (under certain conditions, see below)
  • other entities authorized by law to engage in such transactions (under certain conditions, see rule for more details)

3.  Portfolio Requirement

If an investor is one of the entities described in (2) above, it will also need to meet the portfolio requirement.  The portfolio requirement can be met in one of three ways:

  • Owns securities and other investments with an aggregate market value of at least $2MM;
  • Has had on deposit with a FCM at least $200K in exchange-specified initial margin and option premiums for commodity interest transactions in the 6 months prior to the investment; or
  • Has a combination of the two above.  For example, has $1MM in securities/investments and $100K in exchange-specified initial margin in the 6 months prior to the investment

The above definitions have been shortened for the purpose of providing a general overview.  When determining whether an investor meets the qualified eligible person definition the CPO should take special care to make sure that the investor meets the full definition which can be found here.  Generally the investor will make these representations in the subscription documents which are drafted by the hedge fund attorney.

****

Other related Hedge Fund Law Blog articles include:

Bart Mallon, Esq. runs the Hedge Fund Law Blog.  He can be reached directly at 415-868-5345.

Fund Appreciation Rights

Alternative Hedge Fund Compensation Structure

At the very beginning of this year there was much discussion about the hedge fund compensation structure in light of the horrible returns from 2008.  Many funds lost money but managers aren’t typically subject to the same types of clawback provisions as private equity fund managers.  Additionally some funds had to close shop because of talent retention issues or because the manager realized that reaching a previous high water mark would take too long.  Generally investors who have lost money will prefer to stay in a fund (all else being equal) because of the high water mark – when investors go into a new fund, there high water mark is their initial investment which means they are going to be subject to hedge fund performance fees sooner than in a fund which has previously lost money.

FAR Alternative

As an alternative to the traditional performance fee/ allocation structure, some hedge funds are instituting a different compensation structure called fund appreciation rights (FARs).  Generally this structure provides a more aligned incentive structure for the manager.  Essentially the FARs provide an option like mechanism for the manager.  This option also has the potential to allow the manager to defer recognition of income which may be an added tax benefit for the manager.  [Note: a longer discussion on this issue will be forthcoming shortly.]

Issues with FARs

FARs are new.  It is not known how many groups have implemented FARs or whether they will catch on (or become the next standard).  It is likely that any movement in this area will be driven by the demand (if any) by institutional investors for such products.  FARs are also untested and it is not clear how they will be viewed by the IRS.  As we have recently seen, there has been a big push to disallow the tax advantages of the performance allocation to hedge fund managers and in the current political climate it is likely that the IRS will scrutinize such transactions.

We will continue to research and report on this and other tax structures for hedge fund managers.

****

Other related hedge fund law articles:

Bart Mallon, Esq. of Cole-Frieman & Mallon LLP runs the Hedge Fund Law Blog.  He can be reached directly at 415-868-5345.

Weekly Hedge Fund News Stories | November 30 – December 4

Below are a list of some of the news stories which caught my attention this week.

****

Hedge Fund Carried Interest Tax “Loophole” Repeal? – the hedge fund carried interest “loophole” is again being discussed as a potential issue to be addressed by Congress before the end of the year.  One proposal introduced by Representative Levin (R) has reportedly passed the House twice but is meeting opposition in the Senate.  Watch for a bill to be included as a last minute rider.  For more background, see articles by Boston.com and Reuters.

Wall Street “Transaction Tax” Introduced in House
– A group of Congressmen introduced legislation to tax Wall Street.  According to a press release by Representative Peter DeFazio (D-OR), investment transactions (including stocks, futures, swaps, CDSs, and options) will be subject to “small” transaction taxes which could raise up to $150 billion a year.   The tax would not apply to certain groups like IRAs, mutual funds, and HSAs.  See also a SIFMA press release which discusses this issue.

Florida to Invest $500MM in Hedge Funds – managers who are looking for an allocation from a large pension plan should look toward Florida which is looking to get into hedge funds.  According an article on Pension & Investments, Florida has hired Cambridge Associates as a consultant to help with the search.

Positive November for Hedge Funds – Hedge fund managers gained an average of 1.8% in November according to this Market Watch article.

****

Other articles I liked this week:

Other:

There is a lot of chatter out there about hedge funds and insider trading.  Evidently the SEC is continuing to pursue large hedge fund groups who may have been involved.

****
Bart Mallon, Esq. of Cole-Frieman & Mallon LLP runs the Hedge Fund Law Blog.  He can be reached directly at 415-868-5345.

Hedge Funds, the Secondary Market and PTP Issues

Secondary Hedge Fund Market Poses Issues for Fund Managers

Recently there have been a number of groups springing up to provide a secondary hedge fund market.  While such platforms provide investors with a potential avenue to get out of their illiquid investment (the investment in the fund may be illiquid for a number of reasons including the imposition of a gate provision), they pose problems for the hedge fund manager who will have to deal with the mechanical issues involved in a transfer of the fund interests.  Additionally, as noted in the article below, the manager may have to worry about the PTP issues involved with such potential transfer.

The following article was written by Doug Cornelius of the Compliance Building blog and is reprinted with permission.  All links in the article are from the original.

****

Classification of Private Funds as Publicly Traded Partnerships

Due to the increasing incidence of fund investors who want to transfer their investment fund interests, private investment funds face a risk of being classified as publicly traded partnerships. That would mean the fund would become taxable as a corporation.

A bad result.

Under Internal Revenue Code § 7704, a partnership will be classified as a publicly traded partnership if (1) the fund interests are traded on an established securities market or (2) the fund interests are readily tradable on a secondary market or its substantial equivalent.

The big problem is determining when you have a “substantial equivalent” of a secondary market. Under the regulations, the IRS uses a facts and circumstances test to determine if “partners are readily able to buy, sell, or exchange their partnership interests in a manner that is comparable, economically, to trading on an established securities market.” You hate to get into a facts and circumstances discussion with the IRS.

Fortunately there are some safeguards in the implementing regulations at 26 C.F.R. § 1.7704-1.

Involvement of the Partnership

For purposes of section 7704(b), interests in a partnership are not readily tradable on a secondary market or the substantial equivalent unless (1) The partnership participates in the establishment of the market or (2) The partnership recognizes any transfers made on the market by (i) redeeming the transferor partner or (ii) admitting the transferee as a partner.

Since most fund partnerships require the general partner to approve the the transferee and then admit the transferee, they are unlikely to be able to take advantage of this safe harbor.

De Minimis Trading Safeharbor

The focus of a fund should be on the 2% de minimis safe harbor. 26 C.F.R. § 1.7704-1(j) provides for interests in a partnership to be deemed not readily tradable on a secondary market or the substantial equivalent thereof if the sum of the percentage interests in partnership capital or profits transferred during the taxable year of the partnership does not exceed 2 percent of the total interests in partnership capital or profits.

You want avoid having more than 2 percent of the partnership interests changing hands each tax year.

If you get close to that number there are several transfers that are disregarded transfers for this safeharbor, including:

  • block transfers by a single partner of more than 2% of the total interests
  • intrafamily transfers
  • transfers at death
  • distributions from a qualified retirement plan
  • Transfers by one or more partners of interests representing  50 percent or more of the total interests in partnership

Private Placement Safeharbor

The regulations deem a transfer to not be a trade if it was a private placement. But the regulations have their own definition of a private placement: (1) the issuance of the partnership interests had to be exempt from registration under the Securities Act of 1933,  and (2) the partnership does not have more than 100 partners at any time during the tax year of the partnership. 26 C.F.R. § 1.7704-1(h)

The first prong should be straight-forward for most private funds. The trickier part is the second prong. In some circumstances the IRS can look through the holder of a partnership interest to its beneficial owners and expand the number of partners to include the beneficial holders of that interest.

Passive Income Safeharbor

If a fund is determined to be a Publicly Traded Partnership, it will nonetheless not be taxed as a corporation if 90% or more of the fund’s gross income is passive-type income. [26 U.S.C. § 7704(c)] Passive-type income generally includes dividends, real property rents, gains from the sale of real property, income from mining and oil and gas properties, gains from the sale of capital assets held to produce income, and gains from commodities (not held primarily for sale in the ordinary course of business), futures, forwards, or options with respect to commodities. The income test is on a taxable year basis and must be have been met each prior year.

References:

****

Please also see the post on hedge fund compliance and twitter which includes another reprint of a Compliance Building article.

Other related hedge fund law articles include:

Bart Mallon, Esq. of Cole-Frieman & Mallon LLP runs the Hedge Fund Law Blog.  He can be reached directly at 415-868-5345.

Hedge Fund Events December 2009

The following are various hedge fund events happening this month.  Please email us if you would like us to add your event to this list.

****

December 1

December 1 – December 2

December 1 – December 2

December 1 – December 2

December 1 – December 2

December 1 – December 3

December 1 – December 3

December 1 – December 3

December 2

December 2

December 2

December 2 – December 3

  • Sponsor: European Private Equity & Venture Capital Association
  • Event: EVCA Buyout Forum
  • Location: Paris

December 2 – December 3

December 3

December 3

December 3

December 3

December 3

December 3

December 6 – December 8

December 7 – December 9

December 8

December 8

December 9

December 9 – December 11

December 10

December 10

December 10

December 14 – December 15

December 16